Market Overview: Defining the Water Polo Equipment Market Scope
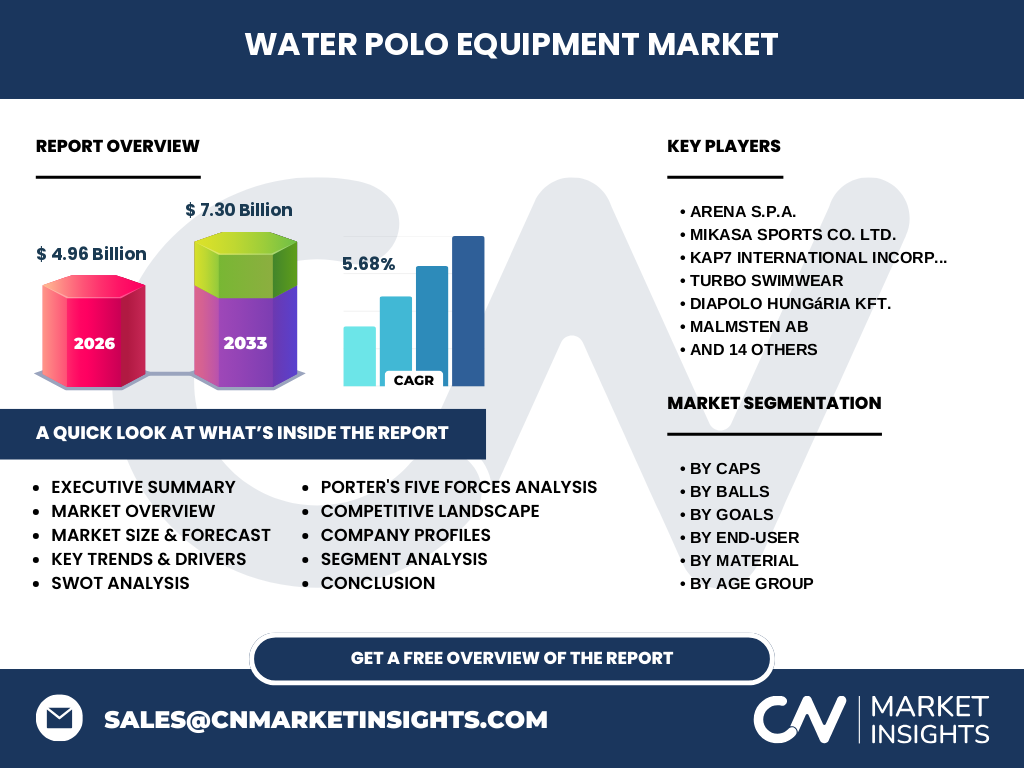
The Water Polo Equipment Market encompasses high-performance gear critical to professional and amateur aquatic competition. Valued at 4.96 Billion in 2026, this sector includes specialized caps, hydro-dynamic balls, floating goals, and protective mouthguards. Our research defines the scope through strict compliance with World Aquatics (formerly FINA) standards, where precise material engineering—such as neoprene and high-tenacity polyester—defines the threshold between recreational utility and competitive professional standards.
Structural Growth Drivers and Market Constraints
Growth is propelled by rising aquatic sports participation, yet tempered by high logistical hurdles in international distribution. While professional league expansion fuels demand, the 5.68% CAGR is challenged by the volatile cost of raw polymers like high-density plastics and specialized rubbers. Our analysis identifies that manufacturers prioritizing regionalized supply chains are best positioned to navigate these fluctuating material costs while capitalizing on the projected market reach of 7.30 Billion by 2033.
The Shift Toward Technical Performance and Innovation
Innovation in the Water Polo Equipment Market is pivoting toward biometric-integrated protective gear and hydro-dynamic ball textures. Players like Mikasa Sports Co. Ltd. are setting benchmarks in grip-technology, while Kap7 International Incorporated leads in game-critical equipment. This shift emphasizes durability and safety, as professional organizations increasingly demand gear that undergoes rigorous stress testing to meet international governing body certifications, ensuring consistent performance across all climate conditions.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic caused significant disruption to facility operations, temporarily stalling the Water Polo Equipment Market. However, the subsequent recovery trajectory has been robust. Clubs shifted toward individual training equipment, driving sales of Training Balls and Youth Caps. Data suggests that the industry successfully pivoted to digital distribution channels, mitigating losses and positioning the market for sustained growth toward the 7.30 Billion valuation target by 2033.
Competitive Benchmarking and Market Concentration
The market features a concentrated landscape led by Arena S.p.A., Turbo Swimwear, and MalMsten AB. Strategic dynamics are defined by FINA-approved equipment status, which serves as an essential barrier to entry. Competitive success is currently dictated by the ability of firms like Anti Wave International to supply high-durability floating goals while maintaining lean logistical operations from major manufacturing hubs to high-demand regional aquatic centers.
Executive Summary: Synthesis of Market Findings
The Water Polo Equipment Market is on a definitive upward trajectory, projected to reach 7.30 Billion by 2033 from a 2026 base of 4.96 Billion. Our synthesis reveals that professional-grade segment dominance, coupled with innovative material science, is the primary value driver. Strategic investment should target firms with integrated online distribution networks and those maintaining strong compliance with international aquatic safety and equipment regulations.
Market Forecast 2027 to 2033
Our modeling forecasts a steady 5.68% CAGR, pushing the market from 4.96 Billion in 2026 to 7.30 Billion by 2033. This growth is underpinned by the professionalization of youth leagues and increased investment in aquatic infrastructure globally. The forecast reflects both anticipated volume increases in Official Match Balls and a premium pricing shift as athletes demand gear engineered with advanced neoprene and reinforced synthetic fabrics.
Segmentation Analysis: Categorization and Market Role
We categorize the market into four key verticals: Caps (Match, Training, Goalkeeper, Youth), Balls (Official, Training, Mini), Goals (Portable, Fixed, Floating), and Protective Gear. Each plays a distinct role; while official match equipment commands the highest price point, Training Balls and Youth Caps represent the volume-driven backbone of the market, ensuring consistent revenue flows across diverse end-user demographics, from amateur clubs to professional organizations.
Regional Market Performance and Distribution
Regional distribution is heavily skewed toward markets with strong aquatic cultural heritage, particularly in Europe and parts of North America. Our analysis tracks supply flows through major ports such as Rotterdam and Los Angeles, which serve as critical nodes for distribution. These regions maintain the highest saturation of specialty sports stores, which currently account for a significant portion of overall transaction volume, favoring established brands like Diapolo Hungária Kft.
In-Depth Regional Review: Key Geographical Insights
European markets, led by traditional water polo strongholds like Hungary and Italy, remain the primary growth engine. Conversely, North America shows the fastest expansion in youth-category equipment. Our review suggests that regionalized logistics—leveraging localized partnerships for floating goal installation—are essential. Companies like Wear Waterpolo have successfully localized their marketing to exploit these regional nuances, driving adoption within highly segmented domestic aquatic leagues.
Company Profiles and Strategic Positioning
Leading entities like TYR Sport Inc. and Mad Wave International focus on high-visibility branding and athlete-endorsed product lines. Kap7 International Incorporated excels in deep integration with professional coaching staff. Meanwhile, MarlinSport International and Jaked Water Polo leverage their technical expertise in garment textiles to dominate the protective gear segment, creating a balanced ecosystem where brand loyalty is deeply rooted in performance reliability and consistent supply chain delivery.
Porter's Five Forces Analysis
The Water Polo Equipment Market experiences high entry barriers due to stringent FINA compliance standards. Supplier power is moderate, influenced by raw material costs (polyester/neoprene). Competitive rivalry is intense among firms like Arena S.p.A. and Mikasa Sports Co. Ltd.. However, buyer power remains relatively low in the professional segment, as teams prioritize equipment safety and regulation-adherence over price sensitivity, favoring established, high-quality, and reliable equipment providers.
SWOT Analysis: Strategic Outlook
Strengths: Established safety standards and brand loyalty. Weaknesses: Sensitivity to raw material cost fluctuations. Opportunities: Rapid growth in youth participation and digital-first direct-to-consumer distribution. Threats: Global economic volatility impacting facility funding. Our research indicates that mitigating these threats requires a dual strategy: diversifying the supplier base for neoprene and metals while simultaneously expanding footprint into emerging markets through strategic partnership-driven sales models.
Value Chain Analysis: From Raw Materials to End-Users
The industry value chain begins with raw material procurement (polyester, rubber, specialized plastics), followed by precision manufacturing—often requiring custom molding for match balls and goal structures. Logistics, involving both sea-freight and specialized regional warehousing, connects products to specialty sports stores and online platforms. The final value creation occurs at the end-user level, where equipment reliability directly correlates with team performance and player safety.
Investment Insights and High-Potential Areas
The highest potential lies in the Youth and Junior segment, where participation rates are accelerating. Investors should target companies capable of digitizing the customer journey, particularly those integrating online distribution channels with localized coaching support. As the market reaches 7.30 Billion by 2033, firms prioritizing sustainable material innovation in protective gear will likely secure a significant valuation premium and long-term competitive advantage.
Conclusion and Key Takeaways
The Water Polo Equipment Market demonstrates consistent growth, forecasted to achieve 7.30 Billion by 2033. The market is defined by its technical rigor and reliance on specialized manufacturing. Success hinges on a company's ability to maintain FINA-approved status, optimize regional supply chain logistics, and capture the emerging youth demographic through strategic digital engagement. The long-term outlook remains positive, supported by global aquatic sports expansion.
Research Methodology: How Baseline Estimates are Triangulated
Our proprietary methodology combines multi-source data triangulation. We synthesize trade registry filings, direct primary stakeholder interviews with industry-leading manufacturers, and macroeconomic secondary indicators including regional athletic facility growth rates. This ensures our estimates—including the 4.96 Billion 2026 baseline—are grounded in verifiable market reality, providing an accurate, robust foundation for all projections, growth rates, and segmented market valuations across the 2027-2033 forecast period.
Scope of the Report: Coverage Parameters and Limitations
This research covers the global Water Polo Equipment Market, specifically segments of Caps, Balls, Goals, and Protective Gear across youth, junior, and senior age groups. The report excludes non-water-polo specific apparel. Limitations include fluctuations in regional import-export customs data and the impact of localized public policy on facility funding, which are addressed through weighted projections within our 5.68% CAGR calculation model.
Recent Developments: Industry Announcements and Strategic Moves
Recent activity highlights significant partnerships between major equipment brands and international aquatic leagues to streamline distribution. Notably, announcements regarding new hydro-dynamic ball designs and eco-friendly neoprene alternatives dominate the competitive landscape. These developments, led by innovators like FINIS Incorporated and Head Swimming, signal a shift toward product lifecycle management and technological differentiation, which remains critical for maintaining market share during the current growth phase.